


Ualett
4.61.28K Reviews
App Specs
- Version
- 2.73.0
- Updated On
- License
- Free
- Downloads
- 500,000+
- Developer
- Cabicash Solutions, Inc
- Categories
- Finance
- Platform
- Android
Screenshots
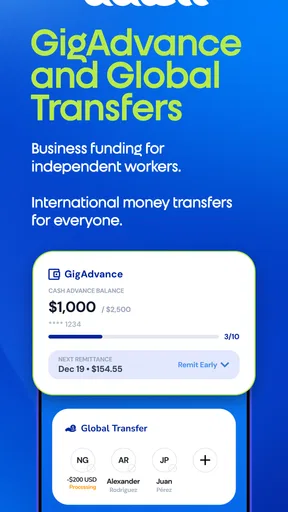
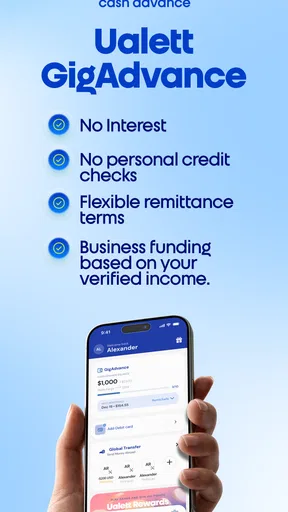
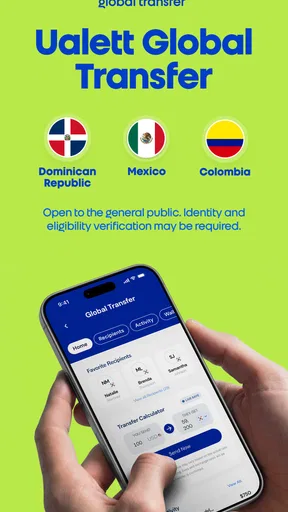
 Analysis by AppCompare
When your income arrives in uneven bursts, ordinary banking apps can feel designed for someone else’s life. Ualett is a finance app from Cabicash Solutions, Inc that is aimed specifically at gig workers, and that focus is the first thing I noticed when judging whether it is worth keeping on a phone. It is free, rated for Everyone, and available for Android devices running version 8.0 or later. I would not describe it as a complete replacement for every banking or budgeting tool, but it can make sense for people whose working week is built around deliveries, rides, freelance jobs, or other flexible work.
My overall impression is that Ualett is most useful when you treat it as a practical money companion rather than a magic solution to irregular cash flow. The app’s current version is 2.73.0, and its presence is already fairly established, with more than 500 thousand installs. It also holds an average rating of 4.6 from roughly 7.6 thousand ratings, alongside about 1.3 thousand written reviews. Those figures suggest that the app has found a real audience, although popularity alone does not remove the need to check whether its approach matches your own work and banking habits.
How Ualett fits into a gig worker’s routine
The strongest reason to try Ualett is simple: gig work does not always follow a predictable payday. A driver may earn more during a busy weekend, a courier may need access to money between completed jobs, and a freelancer may receive payments at times that do not line up with monthly bills. A conventional account can still hold the money, but it may not feel built around that rhythm. Ualett’s identity is different because it starts with the worker’s irregular schedule instead of treating it as an exception.
I found that this changes how I think about the app. It is not primarily interesting because it belongs to the broad finance category; many apps do. Its value comes from narrowing the audience to people who need financial tools to fit around flexible work. That makes it easier to decide whether it is relevant. If most of your income comes from a fixed payroll deposit and you already have a bank account that handles your needs comfortably, Ualett may add another layer without solving a problem you actually have.
For a gig worker, however, the useful question is not only “Can this hold or manage money?” It is “Does this make the gap between earning and spending easier to handle?” That is the standard I would use before installing it. A good experience should reduce the small amount of mental work involved in tracking when money is coming in, what must be covered next, and whether a transfer or payment fits the timing of your work.
A realistic day with uneven earnings
Imagine finishing a morning of delivery work with enough income to cover fuel and lunch, but not enough certainty to know what the evening will bring. Later, a busy period gives you a better result than expected, while a slow afternoon leaves you waiting longer than planned. In that situation, an app aimed at gig workers can be useful because it keeps your financial routine connected to the way you actually earn. Instead of treating the week as one predictable paycheck, you can make decisions around smaller, changing amounts.
My practical advice is to use Ualett alongside a simple personal routine. After a work session, note what must remain available for transportation, food, phone service, and upcoming bills before considering the rest spendable. The app can support the money workflow, but it cannot decide which expenses are essential for you. This distinction matters: convenience is helpful, yet irregular income still requires discipline.
Worth Reading Before You Choose

EA SPORTS FC Mobile 26 Is a Bigger Football Game, but It Takes Time

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy
Another non-obvious benefit of a focused app is psychological rather than technical. When a tool is clearly aimed at gig work, you spend less time trying to force a traditional banking layout into an unusual income pattern. That can make it easier to check your position after a shift or before accepting another job. I would still compare the app’s day-to-day handling with your existing bank, because the most convenient setup may be a combination rather than a full switch.
What the current version tells me
Ualett’s current version, 2.73.0, shows that the product is being maintained rather than left as a one-time experiment. That is important for a finance app, where reliability and continued attention matter more than a flashy first impression. The app was released on August 21, 2018, so it has had time to develop beyond a brand-new launch. I see that history as a positive sign, but not as proof that every part of the experience will suit every user.
The version number is also a useful reminder to keep expectations realistic. A newer release can improve the way an app behaves, but it does not automatically mean that it offers every feature found in a full-service bank, a tax tracker, or a detailed budgeting platform. I would install the latest available version, test the basic workflow with a small amount of activity, and only then decide whether it deserves a central role in my financial routine.
Because Ualett is free, the initial barrier is low. That makes testing easier than committing to a paid financial service. Still, “free” should not be confused with “without consequences.” Before moving important money, I would read the in-app explanations carefully, check how the app fits with my existing accounts, and make sure I understand the timing of any action I plan to use. Finance apps deserve a slower first setup than entertainment apps, even when there is no purchase required to begin.
How the evolution affects existing users
Someone who has used Ualett for a while may care less about the app’s general idea and more about whether the current release feels stable and familiar. A maintained version can be encouraging because it suggests that the developer, Cabicash Solutions, Inc, continues to support the product. At the same time, updates can change navigation or the order of tasks, so existing users should not assume that an old routine will remain identical forever.
My recommendation for established users is to review the app after updating instead of immediately relying on it during a financially important moment. Open the main screens, confirm that your usual actions are easy to find, and check any account or payment details before you need them urgently. This is especially sensible for gig workers who may be working late, moving between locations, or depending on quick access after completing a job.
The current release also matters to people considering a move from another financial app. Rather than comparing only ratings, I would compare the actual effort involved in three moments: receiving or organizing gig income, accessing money when needed, and understanding what remains available afterward. A general bank may offer broader services, while a budgeting app may offer deeper planning. Ualett’s possible advantage is the connection to gig-worker needs, but that advantage is valuable only if it makes those moments simpler for you.
Where it is stronger than the usual alternatives
Traditional banking apps are usually better when you want a broad financial home: established account management, multiple types of products, and a familiar structure for regular income. Budgeting apps are often better when your main goal is categorizing expenses, setting long-term targets, or seeing a detailed household picture. Ualett appeals to a different priority. I would choose it when the main difficulty is the timing and unevenness of gig income rather than a lack of financial categories.
That distinction prevents a common mistake. A person may download Ualett expecting it to replace a bank, a tax adviser, and a budgeting system at once. I would not approach it that way. Gig workers still need to think about taxes, business expenses, emergency savings, and records for their own situation. A focused money app can help organize part of that process, but it should not be treated as professional tax advice or as a guarantee that every financial responsibility has been covered.
There is also a trade-off between focus and breadth. An app built around gig workers may feel more relevant than a general-purpose tool, but a general bank may remain better for people who need several account types or a long-established financial relationship in one place. If your work income is only a small side activity and your current bank already gives you a clear way to separate it, adding Ualett may create duplication rather than clarity.
Small workflows that make the app more useful
One practical workflow is to separate “earned” from “safe to spend.” After each work period, I would first account for costs that made the income possible, such as transport or equipment, then consider personal spending. This prevents the common error of treating every incoming amount as disposable. Ualett can be part of that routine, but the important insight is the order of decisions: protect operating money before rewarding yourself with the remainder.
A second useful approach is to check the app at consistent points instead of opening it every few minutes. For example, review it after a shift and again before a major bill is due. That creates a repeatable habit without turning your finances into a constant source of anxiety. Irregular work already produces enough uncertainty; a simple checking rhythm can make the information more actionable.
A third trade-off involves using Ualett with, rather than against, an existing bank account. Keep the account that handles your stable obligations if it is working well, and use the gig-focused tool for the part of your finances that feels less predictable. This arrangement may be more useful than forcing every payment, deposit, and bill through one app. The best setup is the one that leaves you with fewer surprises, not necessarily the one with the fewest apps.
Finally, test your personal recovery plan before you depend on the service. Make sure you know how you would access important information if your phone were unavailable, your connection were poor, or you needed to change devices. That is not a criticism unique to Ualett; it is a sensible habit for any mobile finance product. Convenience should be paired with a backup method for essential records and account details.
Limits I would consider before switching
The biggest limitation is that the gig-worker focus may be too narrow for some households. If you want a complete view of shared finances, detailed spending analysis, or tools designed around regular salary income, another app may be a better primary choice. Ualett can still have a role, but I would not expect a specialized tool to replace every service that a larger banking or budgeting platform provides.
There is also a learning curve whenever money is moved into a new system. Even a straightforward interface can require new habits, especially if you already receive gig income through several platforms. The more fragmented your work is, the more important it becomes to decide what Ualett is responsible for. If you cannot explain which money belongs there and which money stays elsewhere, the app may add confusion instead of reducing it.
People who need guaranteed access to a particular financial feature should verify that it fits their needs before making a switch. I would pay close attention to the actions that matter most in my own routine, such as how I receive money, how I use it afterward, and how easily I can review activity. The right app is not determined by a high rating alone. It is determined by whether the everyday path from work to usable money feels dependable and understandable.
Privacy and security should also be part of the decision, even though they are not exciting topics. I would avoid rushing through setup, use a strong device lock, and keep the app updated. I would also be cautious about using public networks for sensitive financial actions. These habits do not make Ualett better or worse by themselves, but they are essential when a phone becomes part of your money management.
Who should try it, and who should skip it
I would recommend giving Ualett a serious look if you earn through gig platforms, experience changing income from week to week, and want a finance app that recognizes that pattern. It is especially worth testing if your current bank feels too general and your biggest frustration is organizing money around completed jobs rather than a fixed payday. The free price makes a low-risk trial possible, provided you start carefully.
I would be more hesitant if you already have a reliable banking setup, rarely earn outside a regular payroll schedule, or need extensive household budgeting in one place. I would also skip making it your only financial tool if you require specialized planning, detailed tax support, or a broad set of banking products. In those situations, a traditional bank or dedicated budgeting service may be the stronger foundation, with Ualett considered only for a specific side-income workflow.
What I would watch next
For future updates, I would watch whether the app continues to make gig income easier to understand without becoming cluttered. The best evolution would preserve the focused experience while making important money movements clearer for both new and existing users. I would also look for improvements that reduce uncertainty around timing, organization, and the transition between earning and spending, because those are the moments that define whether the app is genuinely useful.
I would not judge future changes by version numbers alone. What matters is whether a release helps a courier, driver, freelancer, or other independent worker complete a real task with fewer steps and fewer doubts. Existing users should look for smoother daily routines, while new users should compare the current experience with the exact problem they want to solve. That keeps expectations grounded in practical value rather than novelty.
After reviewing Ualett as a finance app, I see it as a focused option with a clear audience, not a universal banking answer. Its free access, Everyone rating, long availability, and current version make it approachable, while its gig-worker orientation gives it a reason to exist beside more general alternatives. The best reason to use Ualett is not that it does everything; it is that it may fit the uneven rhythm of gig income better than a conventional tool.
I would try it if my earnings changed from job to job and I wanted a dedicated place to build a more deliberate routine. I would keep my expectations measured, test the important actions first, and continue using another service where it was stronger. For the right worker, that balance could make Ualett a helpful part of everyday money management. For everyone else, the specialization may be less useful than the familiarity and breadth of the financial tools they already have.
Pros
- Fast access to earned wages without waiting for the usual payday.
- Simple mobile application with an easy-to-follow advance request process.
- Can help cover unexpected expenses between regular paychecks.
- Funds are sent directly to a linked bank account or eligible card.
- Useful budgeting visibility through information about available earnings.
Cons
- Advance fees may reduce the amount you ultimately take home.
- Eligibility depends on employer participation and account verification.
- Available advance limits can be lower than expected for new users.
- Repayment is typically deducted from a future paycheck automatically.
- Not available in every location or for every employment arrangement.
FAQs for Ualett
What is Ualett and how does it work?
Ualett is a digital financial platform designed to help users manage money and access selected financial services through a mobile app. Depending on your country and eligibility, it may support features such as account management, payments, transfers, or other wallet-related tools. After installing it, you normally create an account, verify your identity, and use the available services from the app dashboard.
Is Ualett available for everyone, and what are the registration requirements?
Availability can depend on your country, age, residency, and the services offered in your region. During registration, Ualett may request personal information such as your full name, phone number, email address, identification details, or proof of identity. Requirements can vary, so users should check the official terms and eligibility conditions before submitting documents or relying on the app for essential financial transactions.
Is Ualett safe to use for payments and personal information?
Ualett uses account access controls and security procedures intended to protect user information and transactions, but no financial application is completely risk-free. Use a strong, unique password, keep your phone updated, activate any available security verification, and never share login codes. Download the app only from an official store and contact support immediately if you notice suspicious activity.
Are there fees or limits when using Ualett?
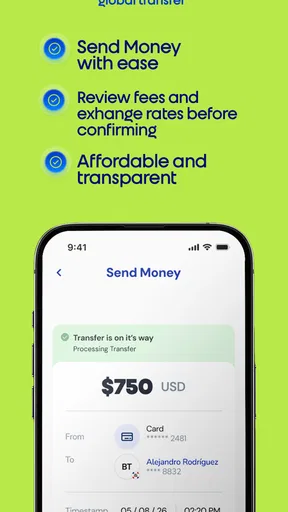
Fees and transaction limits may apply depending on the specific Ualett service, your location, payment method, account status, and the type or amount of transaction. Some actions may be free while others can include processing, withdrawal, transfer, or currency-related charges. Before confirming a transaction, review the displayed cost, limits, and applicable terms because pricing may change over time.
What should I do if a Ualett transaction fails or my account is blocked?
If a transaction fails, first check your internet connection, account balance, recipient details, and whether your account has completed the required verification. Avoid repeating the payment if you are unsure whether the first attempt was processed. Save confirmation messages or screenshots, then contact Ualett support through the official app or website. Never rely on unofficial social-media contacts requesting passwords or verification codes.


